Last week delivered a compelling combination of artificial intelligence breakthroughs and monetary policy anticipation that sent markets climbing across the board. As we head into what many consider a pivotal Federal Reserve meeting this Wednesday, let me break down the key developments shaping your investment landscape and what they might mean for your financial planning.
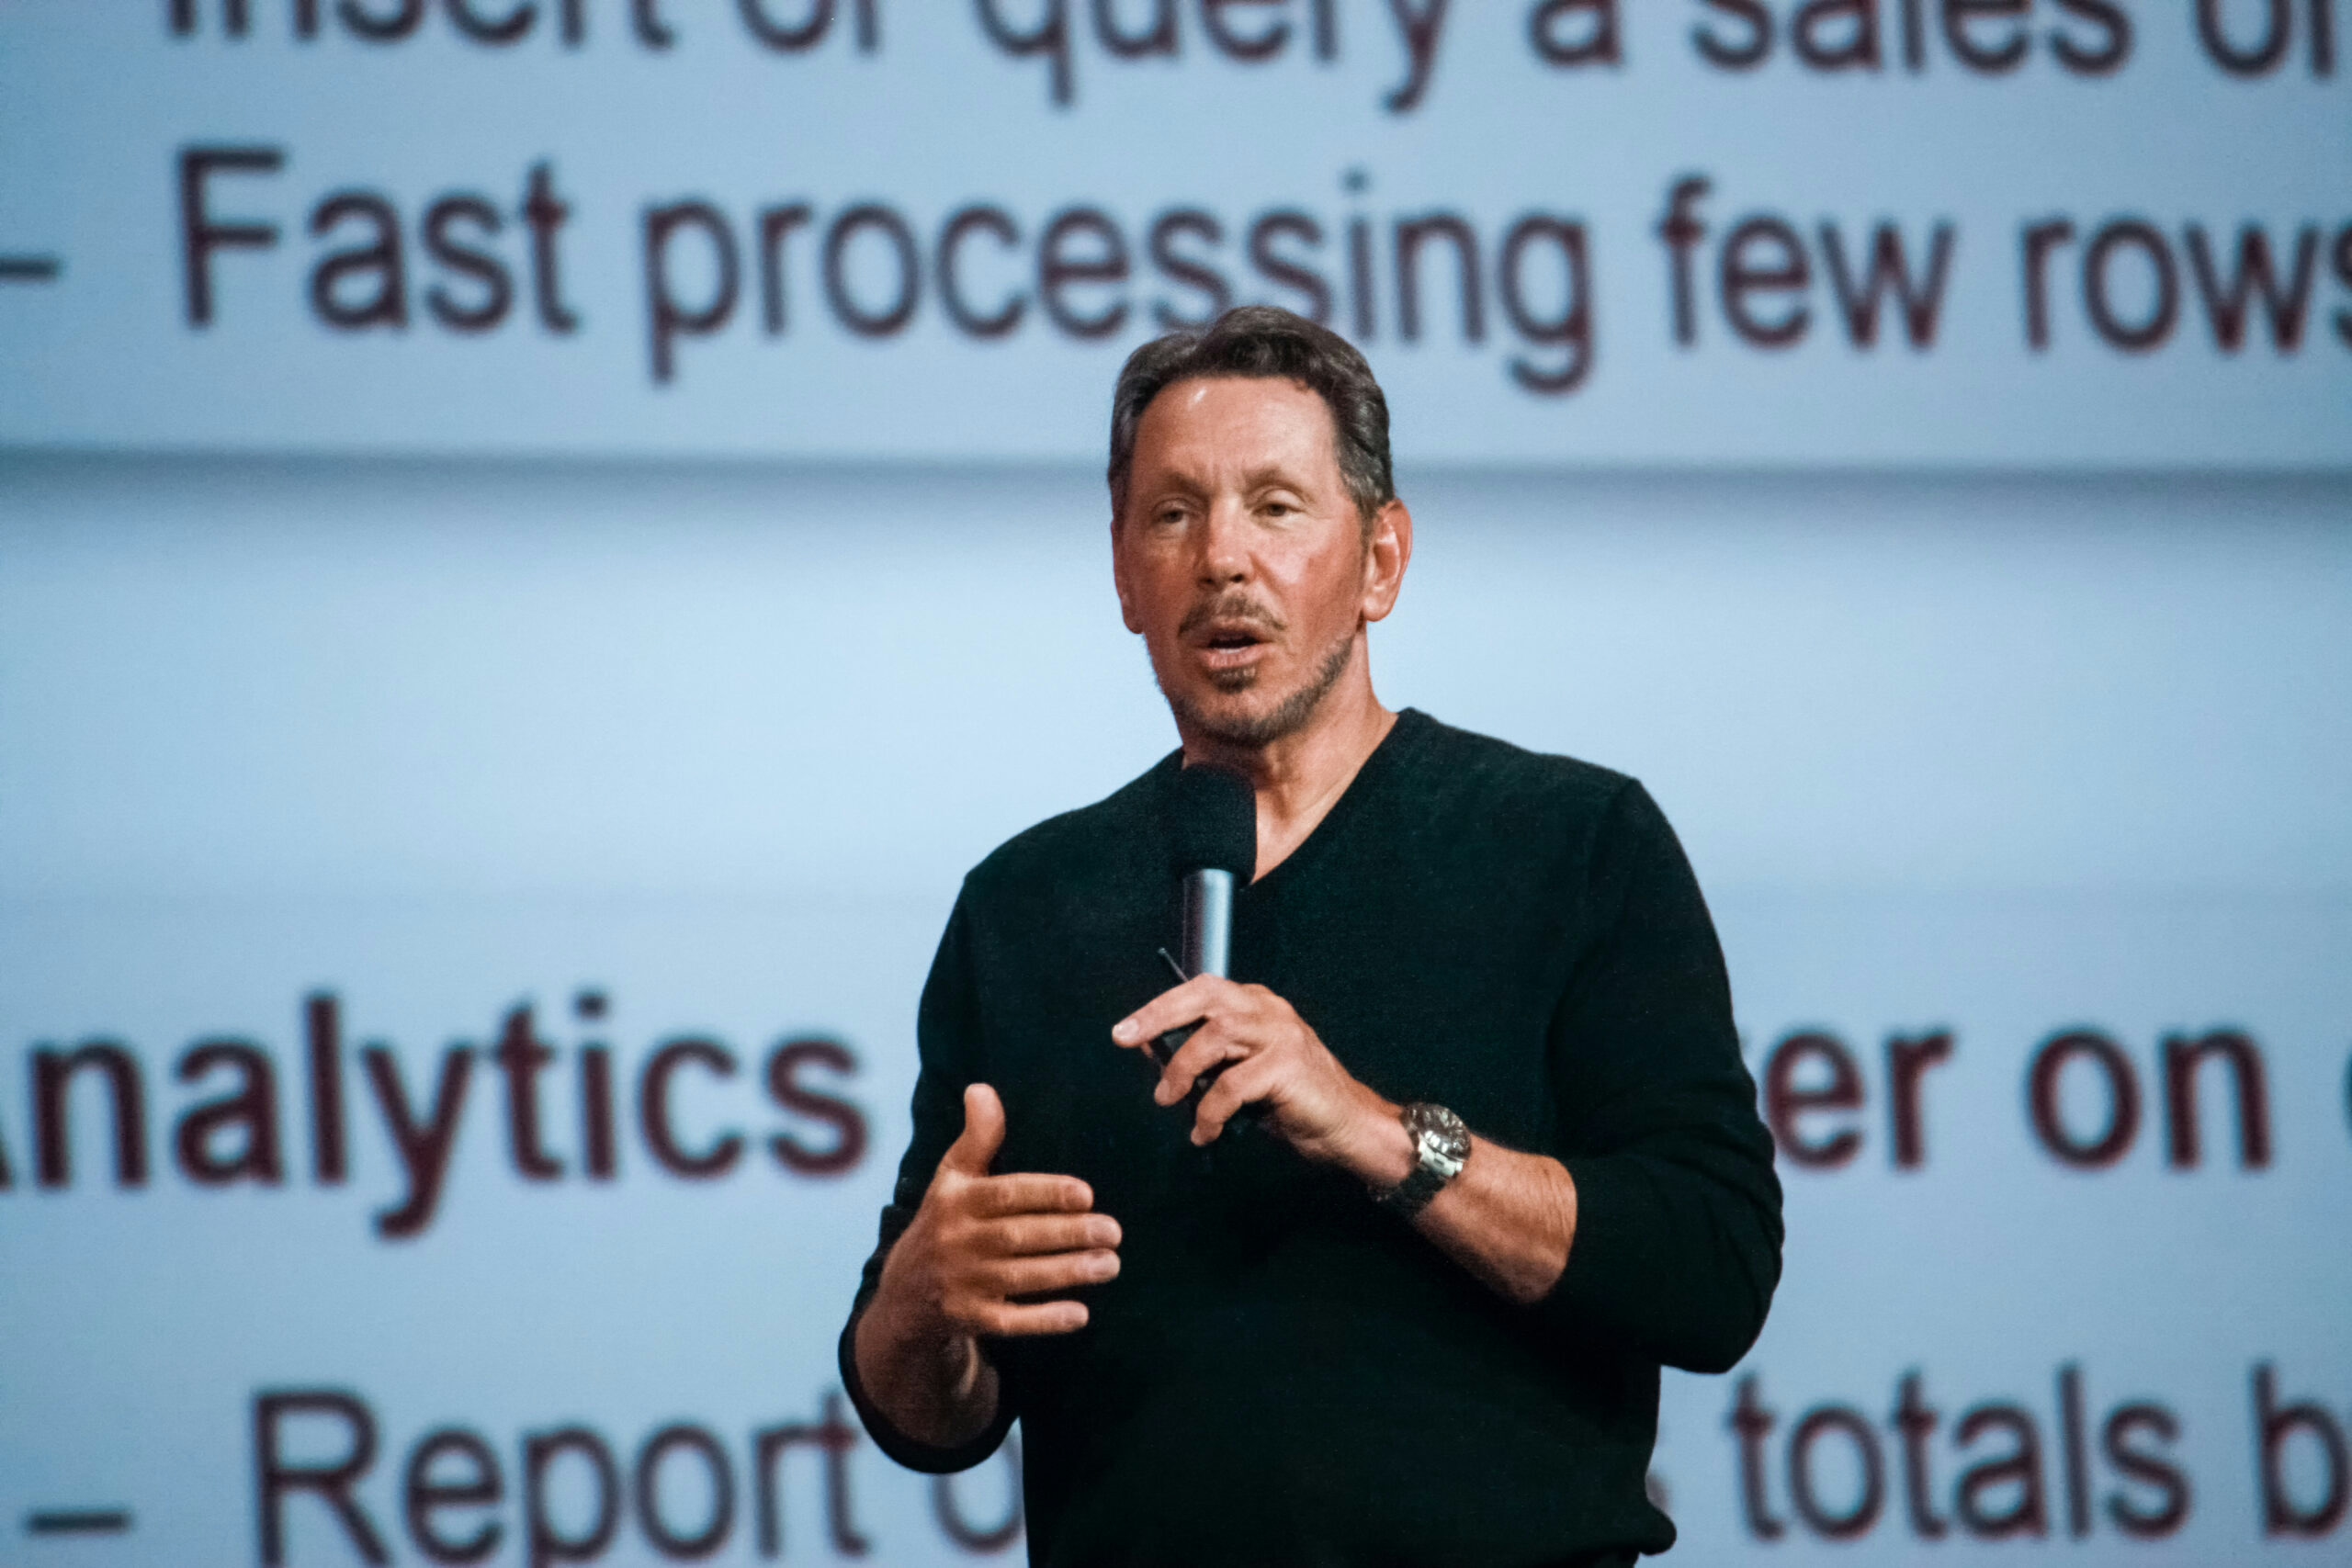
Larry Ellison briefly became the world’s wealthiest person last week, driven by Oracle’s record-breaking partnership with OpenAI and soaring stock performance.
Oracle’s AI Partnership Sparks Technology Sector Surge
Oracle Corporation’s announcement of a groundbreaking $300 billion cloud computing agreement with OpenAI sent shockwaves through the technology sector this week. Oracle’s stock experienced its best single day since 1992, surging over 36%. This five-year agreement, beginning in 2027, represents one of the largest cloud contracts in history and demonstrates the massive scale of AI infrastructure investment.[i]
The ripple effects extended throughout the tech sector, with the S&P 500’s technology component gaining 3.30% for the week. This AI-driven momentum reflects how businesses are prioritizing artificial intelligence investments as their primary growth strategy heading into a potential rate-cutting cycle.
The positive sentiment wasn’t limited to tech stocks. All major indexes participated in the rally:
- S&P 500: +1.75%
- NASDAQ: +2.16%
- Russell 2000: +0.6%
International markets joined the upward movement as well, with foreign stocks rising 1.38% and emerging market stocks gaining 1.71%.
Bond markets continued their recent trend, with the 10-year U.S. Treasury yield ending the week at 4.068%. Notably, the government successfully auctioned a significant amount of new Treasury debt that met with strong investor demand, indicating healthy appetite for government bonds.
Current Inflation Data Shows Mixed Signals for Retirement Planning
Understanding inflation trends remains crucial for retirement planning, and August’s data presents a nuanced picture. The Consumer Price Index (CPI) headline number rose 0.4% in August—the highest monthly spike since January. However, the Producer Price Index (PPI) actually decreased by 0.1%, providing some balance to the inflation narrative.
Within August’s CPI report, several categories impacted everyday expenses:
- Automobile prices rose
- Grocery costs increased 0.6%
- Clothing prices moved higher
-
- Automobile prices rose
Interestingly, July’s PPI was revised downward from 0.9% to 0.7%, reflecting how tariff costs to businesses may have been initially overestimated.
The Federal Reserve is widely expected to implement a 0.25% interest rate cut this week, with the weakening job market serving as the primary justification for this monetary policy adjustment.
Health Insurance Inflation Impacts Cherry Hill Area Retirees
Healthcare insurance presents a growing concern for retirees and families. Premium increases are accelerating at the fastest pace since 2010, with employer-sponsored health insurance costs rising nearly 9% for 2026.[ii] My own experience illustrates this challenge perfectly—Retirement Refined LLC recently received our health insurance renewal for November 1st with a staggering 19.8% increase. Similarly, my wife’s employer faced average premium increases just under 10%.
The political dimension adds another layer of uncertainty. As Congress faces another potential government funding deadline at month’s end, Democrats are reportedly holding firm on extending Obamacare subsidies beyond 2025. If these COVID-era subsidies expire, many residents could face even higher healthcare premiums.
Savings Account Rates Decline as Fed Policy Shifts
If you’re like many people I work with, you’ve been enjoying historically attractive rates on high-yield savings accounts for your emergency funds. However, these rates are beginning their expected decline as markets anticipate Fed rate cuts.
Consider this: in August 2024, popular high-yield savings accounts offered rates around 4.3%. Today, many of these same accounts offer 3.5%, and further declines seem likely. While 3.5% remains substantially better than the near-zero rates we experienced just a few years ago, it’s important to understand your options as this trend continues.
Some investors consider moving to short-term bond funds seeking higher yields, but remember that these alternatives come with principal risk and lack FDIC insurance protection. If interest rates continue declining, high-quality short-term bonds might appreciate. Conversely, if inflation resurges and pulls rates higher, you could experience pressure on your principal.
Key Economic Reports to Monitor This Week
Three important economic releases this week will provide additional insight into our economic trajectory:
- Tuesday: August Retail Sales report, indicating consumer spending confidence
- Wednesday: New mortgage and refinance applications data
- Wednesday: Fed Chair Jerome Powell’s interest rate policy announcement
These reports will help clarify whether recent market optimism aligns with underlying economic fundamentals.
Moving Forward with Confidence
The current environment presents both opportunities and challenges. While AI developments and potential Fed policy changes create market enthusiasm, underlying factors like ongoing inflation and changing interest rate environments require careful consideration in your retirement planning.
If you’d like to discuss how these market developments might impact your specific retirement strategy, I’m here to help you navigate these complex financial waters.
All recent market data sourced from the Wall Street Journal, September 12, 2025.
The opinions voiced in this material are for general information only and are not intended to provide specific advice or recommendations for any individual.
[i] https://www.cnbc.com/2025/09/10/oracle-stock-cloud-backlog-ai.html
[ii] https://www.mercer.com/en-us/insights/us-health-news/employers-prepare-for-the-highest-health-benefit-cost-increase-in-15-years/